Analysis · Business & Finance
Why Slower Wage Growth May Not Bring Cheaper Services
Cooling orders and worsening delivery delays expose a pricing dilemma: businesses still face rising costs, while households have less purchasing power to absorb them.

Slower orders should give suppliers room to catch up. October 2026’s US services survey instead showed new-order growth cooling while delivery delays became more widespread. That divergence matters more for corporate pricing decisions than a modest decline in the headline activity index.
The new-orders index fell to 55.9 in October from 59.8 in September, while supplier deliveries rose to 56.7 from 53.2, according to Reuters’ November 4 report. For deliveries, readings above 50 indicate slowing rather than improving performance. Orders were still expanding, but with less breadth; delays were becoming more prevalent.
This is a potential margin squeeze, not proof of one. Businesses may face persistent input pressure just as their customers become harder to charge. Slower wage growth helps with only part of that equation.
Cooling demand is not the same as cheaper supply
October’s services PMI eased to 54.5 from September’s 54.9. The prices-paid index slipped to 73.0 from 74.0 over the same period. These are diffusion indexes: they describe the balance of reported changes, not percentage increases in output or prices. October’s prices reading does not mean input costs rose by 73%.
Nor does the survey establish why deliveries slowed. Strong demand, supply disruption and operational bottlenecks can produce similar responses. The combination of weaker order momentum and longer delivery times warrants attention, but cannot identify the cause by itself.
For a business, however, the mechanism is straightforward. An unreliable delivery can cost more than its invoice price. Expedited transport, substitute materials, idle staff and rescheduled appointments can all raise the cost of completing a service. Those are possible consequences, not outcomes measured by this survey.
Procurement exposure also differs sharply. A business dependent on physical supplies faces a different problem from one selling predominantly staff time. Contracts, inventory policies and supplier concentration determine how quickly any disruption reaches the income statement.
The balance sheet matters too. Carrying additional supplies may protect operations, but ties up cash. A financially stronger business can tolerate that allocation more readily than a competitor already managing tight liquidity. Supply uncertainty can therefore widen competitive differences even before anyone changes a customer price.
Wages are only part of the labour bill
The Bureau of Labor Statistics’ September 2026 Employment Cost Index release, published October 30, showed civilian wages rising 0.7% in the quarter ending September, seasonally adjusted, compared with 0.9% in the preceding quarter. But benefits rose 0.9% in the September quarter, leaving total compensation costs up 0.8%.
Moderating wages are not falling wages. And a slower increase in wages does not translate mechanically into an equivalent slowdown in the full employment bill.
The more useful operating measure is labour cost per unit of service delivered. If compensation grows more slowly but staff complete fewer billable jobs, unit costs can still rise. Conversely, better scheduling, fewer administrative errors or improved equipment can accommodate higher pay without requiring matching price increases.
That is why productivity belongs in the inflation argument. Wage growth alone cannot tell us whether a business has gained room to reduce prices, rebuild margin or simply stop raising prices as quickly.
The distinction between lower inflation and cheaper services is essential. Even genuine cost relief may produce smaller price increases rather than outright price cuts. Whether customers receive the benefit depends partly on competition and on how much pricing power the business retains.
Households face the same costs from the other side
The BLS release also reported private-industry wages up 3.1% over the year ending September 2026, not seasonally adjusted, while inflation-adjusted wages fell 0.6%. These are economy-wide private-industry measures, not estimates specifically for services workers.
The household accounts reinforce the purchasing-power constraint. In BEA’s September 2026 personal income and outlays release, published October 29, real disposable personal income declined 0.3% from August. The personal saving rate was 3.8%.
Nominal consumption expenditure increased 0.5% that month, but real consumption rose less than 0.1%. Households spent more dollars with barely any increase in inflation-adjusted consumption. That does not establish that every household is retrenching, or that services demand is about to contract. It does challenge the assumption that rising nominal spending necessarily represents robust volume growth.
For a service provider, cost pass-through is therefore a demand decision as well as an accounting decision. A higher price may preserve contribution per transaction while reducing transaction numbers. Customers can trade down, visit less often or postpone discretionary purchases.
The resulting loss of volume can spread rent, technology and management costs over fewer sales. A price increase designed to protect margin can then undermine it.
Who absorbs the pressure?
Businesses have several possible responses. None is established as the dominant response by the evidence here.
They can absorb costs, leaving owners with less profit than otherwise. They can reprice selectively, shifting more of the burden towards customers with fewer substitutes. They can change suppliers, exchanging potential savings for switching costs and execution risk.
They can also invest in productivity. Yet the incentive and the financing may point in opposite directions: pressure on unit costs makes investment more valuable, while weaker cash generation makes it harder to fund.
Restrained hiring offers another route. That could limit payroll growth without immediate price changes, but risks poorer service or lost capacity. If adopted broadly, it could further weaken household income growth and feed back into demand.
For monetary policy, the tension is similarly uncomfortable. Softer demand can curb pass-through, but does not itself repair a delivery bottleneck. September 2026’s PCE inflation rates—3.6% annually overall and 3.1% excluding food and energy—describe broad consumer prices, not services inflation alone. They offer context, not a direct measure of this corporate dilemma.
The evidence supports scrutiny of US services inflation and profit margins; it does not support declaring that aggregate margins have already fallen. That conclusion requires financial evidence on realised prices, volumes, costs and productivity.
The consequential question is not simply whether wages slow. It is whether businesses can deliver services more efficiently before customers lose the capacity to pay more. Without that improvement, disinflation may arrive through weaker profits, restrained hiring or reduced consumption—not through an easy decline in costs.
Sources and References
- Reuters, syndicated by StreetInsider: October 2026 US services activity, orders, deliveries and prices paid, November 4, 2026.
- U.S. Bureau of Labor Statistics: Employment Cost Index — September 2026, released October 30, 2026.
- U.S. Bureau of Economic Analysis: Personal Income and Outlays, September 2026, released October 29, 2026.
This content is for information only and is not investment advice. See our disclaimers.
Spotted an error? Request a correction · Corrections Policy
Related stories
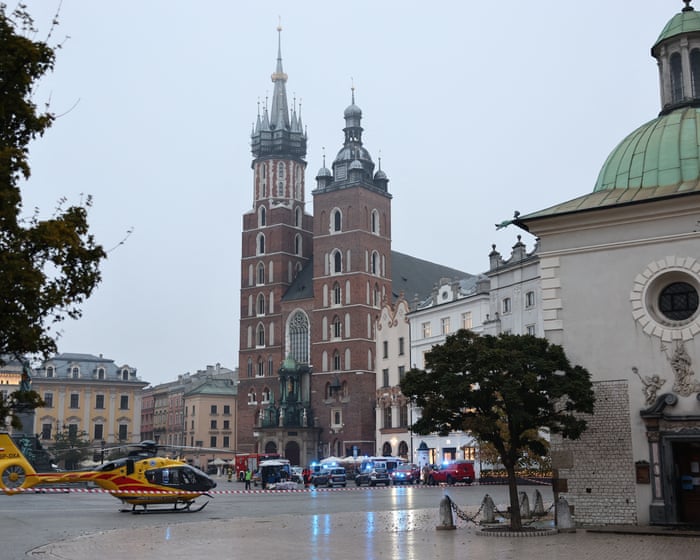
Six dead after gunman opens fire ‘at random’ in Kraków market square
Reports say man fired shots from from his car in Poland’s second city before being wounded by police while trying to flee Kraków shooting – latest updates Six people have been killed and 15 injured after a shooting in a market square in Kraków, Poland. A man who had driven into the square at about 3pm began “firing at random people from his car”, according to a statement by local police on X. Continue reading...
The Guardian ·
Five killed and at least 10 injured in Krakow shooting
Five people have been killed and at least 10 injured in a shooting near the main market square in Krakow, Poland.
Al Jazeera ·
Poland: At least 5 killed in shooting in Krakow, police say
At least five people were killed and more than a dozen injured after a shooter opened fire in a market square in Krakow.
Deutsche Welle ·

At least six people killed in shooting in Polish city of Krakow, police say
A shooting in the main market square of Krakow in Poland killed at least six people and wounded more than a dozen on Saturday, local police said, adding that the gunman was a Polish citizen and that they had shot and wounded him. Mass shootings are uncommon in the country.
France 24 ·

UK cannot 'cherry pick' EU single market deal, Barnier tells BBC
The former Brexit negotiator says EU countries would reject any British attempts to follow economic rules "a la carte".
BBC News ·

Banking scandal topples Paraguay leader
Paraguay’s ousted president Santiago Peña has been placed under house arrest after senators unanimously voted to remove him over a banking scandal. The collapse of Ueno Bank left nearly three million customers unable to access their savings. Peña denies any wrongdoing, while his successor, Pedro Alliana, has pledged to compensate those affected.
France 24 ·